Financing the Educational Journey Guide to Student Financial Aid
Nearly every student is eligible for some form of financial aid whether it comes from the government, their college, or a private organization such as JELF. Financial aid comes in the form of grants, scholarships, work-study programs or loans. Students who do not qualify for need-based aid, such as Pell Grants or subsidized federal loans, are typically still eligible for unsubsidized federal loans regardless of their family income or financial circumstances.
Be sure to prepare for college effectively by making informed financial decisions early on. Explore JELF's resources for saving, budgeting, and understanding the costs of higher education. Access our College Readiness Test to ensure you're on track with your college savings!
Understanding the True Cost of College
College expenses extend far beyond tuition. To effectively plan and budget, families must understand the full scope of costs associated with higher education.
Understanding and planning allow families to make informed decisions, manage their finances effectively, and reduce the financial burden of higher education. This approach ensures a clearer path to achieving educational goals without unexpected financial strain.
Tuition and Fees
- Tuition:
- Public Institutions: Typically lower than private colleges, with significant cost differences between in-state and out-of-state students.
- Private Institutions: Generally more expensive, but often offer substantial financial aid packages.
- Mandatory Fees:
- Technology Fees: Covering the cost of campus technology resources.
- Activity Fees: Funding student organizations and activities.
- Lab Fees: Additional charges for science or computer lab courses.
Room and Board
- On-Campus Housing:
- Dormitory Costs: Vary by institution and room type (single, double, suite-style).
- Meal Plans: Often mandatory for freshmen, with various options based on the number of meals per week.
- Off-Campus Housing:
- Rent: Influenced by the local real estate market and proximity to campus.
- Utilities and Internet: Monthly costs for electricity, water, internet, and other utilities.
- Food: Budgeting for groceries and dining out, which can fluctuate significantly.
Books and Supplies
- Textbooks:
- New vs. Used: Used or digital textbooks are often cheaper.
- Rentals: An economical option for students not needing to keep the books.
- Supplies:
- Course-Specific Materials: Includes lab equipment, art supplies, or software licenses.
- General Supplies: Pens, notebooks, and other everyday items.
Personal Expenses
- Transportation:
- Public Transport: Bus passes or subway fares for commuting.
- Personal Vehicle: Costs for gas, parking, insurance, and maintenance.
- Healthcare:
- Insurance: Health insurance premiums if not covered by a parent’s plan.
- Medical Expenses: Out-of-pocket costs for doctor visits, medications, and emergency care.
- Miscellaneous:
- Clothing, Entertainment, and Social Activities: Regular budgeting for these personal items is crucial to avoid overspending.
Additional Fees
- Application Fees: Costs associated with applying to multiple colleges.
- Orientation Fees: Fees for attending mandatory orientation programs.
- Graduation Fees: Costs for cap and gown, diploma processing, and graduation ceremonies.
- Renters Insurance: A common requirement for students living off-campus or in certain on-campus housing, covering personal belongings and liability.
Travel Costs
- Transportation to and from School: Especially relevant for out-of-state students, including flights or long drives.
- Holiday Travel: Budgeting for trips home during breaks and holidays.
Internship and Study Abroad Expenses
- Unpaid Internships: Budgeting for living expenses if internships don’t provide a salary.
- Study Abroad Programs: Additional costs for travel, visas, accommodation, and program fees.
Understanding the costs associated with different types of colleges and their locations is crucial for effective financial planning. The following charts provide a detailed breakdown of tuition fees, advantages, and challenges for various college types, as well as the impact of location on living expenses and overall costs. This information can help students and families make informed decisions about higher education options.
| Type of College | Tuition and Fees | Advantages | Challenges |
|---|---|---|---|
| Community Colleges | Generally lower tuition than four-year institutions. In-district and out-of-district rates may apply. | Affordable general education courses. Flexible schedules for students who work. Potential savings before transferring to a four-year institution. | Fewer campus resources and extracurricular activities. Transfer credits may not always be accepted by four-year institutions. |
| Four-Year Public Universities — In-State | Generally lower tuition for state residents, with costs varying by state and institution. | Lower tuition for residents. Access to state-sponsored scholarships and grants. Wide selection of academic programs. | Competitive admissions at popular institutions. Limited availability of some scholarships and programs. |
| Four-Year Public Universities — Out-of-State | Typically higher tuition for nonresidents, although some schools offer discounts or merit scholarships. | Broader selection of institutions and specialized programs. Opportunities for new experiences and networking. | Higher tuition and travel expenses. Limited eligibility for certain state-funded financial aid programs. |
| Private Universities | Often higher published tuition, but institutional grants and scholarships may significantly reduce actual costs. | Potentially generous financial aid packages. Smaller class sizes, personalized attention, extensive resources and strong alumni networks. | High published costs without financial aid. Competitive admissions and scholarships. Financial aid policies vary significantly. |
| Vocational Schools | Costs vary widely depending on program length, institution and certification requirements. | Shorter programs. Hands-on training for specific careers. Opportunities to enter the workforce sooner. | Limited academic flexibility. Additional certifications or licensing may be required. Some programs have limited financial aid eligibility. |
| Merit-Based Financial Aid | Scholarships awarded based on academic achievement, leadership, athletics, artistic talent or other accomplishments. | Reduces educational expenses without repayment. May make higher-cost institutions more affordable. | Highly competitive. May require maintaining a minimum GPA or meeting other renewal requirements. |
| Need-Based Financial Aid | Financial assistance determined by a student's demonstrated financial need and applicable eligibility criteria. | Helps make college accessible to students with limited financial resources. Grants and scholarships generally do not require repayment. | Eligibility and award amounts vary. Funding may not cover all demonstrated need. Some assistance requires annual reapplication. |
How College Location Impacts Costs
| Location | Cost of Living | Advantages | Challenges |
|---|---|---|---|
| Urban Campuses | Generally higher housing, transportation and everyday living expenses. On-campus housing may be convenient but costly. | Access to internships, employment, cultural activities, public transportation and professional networking. | Higher overall living expenses. Competition for affordable housing. Potential distractions. |
| Rural Campuses | Often lower housing and everyday living expenses, although transportation costs may be higher. | Potentially lower overall cost of attendance. Close-knit communities and fewer urban distractions. | Fewer nearby internships and employment opportunities. Limited public transportation and access to some amenities. |
| Northeast | Generally higher tuition and living expenses, particularly in major metropolitan areas such as Boston and New York City. | Wide range of prestigious universities, established professional networks and cultural opportunities. | High housing and transportation expenses. Competitive admissions at many institutions. |
| Midwest | Often more affordable housing and living expenses, particularly outside major metropolitan areas. | Strong public university systems. Potentially good value for in-state students. Affordable college-town living in many locations. | Fewer nearby internship opportunities in some rural areas. Harsh winters may increase transportation and heating expenses. |
| South | Often lower tuition and living expenses than the Northeast and West Coast, although costs vary considerably by city. | Wide selection of public and private universities. Strong state scholarship programs in some states. Growing employment markets. | Rising housing costs in rapidly growing cities. Limited public transportation in some areas. |
| West Coast | Higher housing and living expenses in major metropolitan areas, particularly in California. Out-of-state public tuition can also be substantial. | Renowned public university systems. Access to major technology, entertainment and other employment industries. | High housing and transportation costs. Competitive admissions at popular institutions. Higher tuition for many nonresident students. |
The college with the lowest published tuition is not always the most affordable. Compare each school's net price—the total cost of attendance minus grants and scholarships—rather than tuition alone. Consider housing, transportation, books, personal expenses and the amount you may need to borrow.
For eligible Jewish students, JELF's interest-free, last-dollar loans can help bridge remaining financial gaps after other available financial aid has been considered.
Using Cost Estimators and Calculators
Many colleges offer online cost calculators that provide an estimate of tuition and fees, room and board, and other expenses based on specific student information. These tools can give you a realistic idea of the total cost of attendance, helping you plan more effectively. Take advantage of these calculators early in your planning process to set accurate financial expectations.
Creating a Detailed Budget
- Break Down Estimated Costs into Categories: Divide your college expenses into clear categories such as tuition, housing, food, books, transportation, and personal expenses. This makes it easier to manage and monitor your spending.
- Track All Expenses: Keep a detailed record of all expenses, both expected and unexpected. Use budgeting apps or spreadsheets to help you stay organized. Regularly compare your actual spending to your budget to ensure you stay on track.
- Adjust as Necessary: Be prepared to adjust your budget as needed. College costs can change, and personal circumstances can vary, so flexibility is key. Regularly review your budget and make adjustments to address any discrepancies or changes in your financial situation.
- Plan for Unexpected Costs by Setting Aside a Contingency Fund: It's important to have a contingency fund for unplanned expenses such as medical emergencies, car repairs, or sudden increases in living costs. Aim to set aside a small percentage of your budget to cover these unexpected costs, providing a financial safety net.
Utilizing Financial Aid and Scholarships
- Maximize Financial Aid: Complete the Free Application for Federal Student Aid (FAFSA) as early as possible to determine your eligibility for federal grants, loans, and work-study programs. Stay informed about deadlines and required documents to ensure you don't miss out on available aid.
- Apply for Scholarships: Continuously search and apply for scholarships throughout the year. Many scholarships have specific criteria and deadlines, so it's important to stay organized and keep track of applications. Scholarships can significantly reduce the overall cost of college.
Managing Day-to-Day Expenses
- Limit Discretionary Spending: Be mindful of non-essential expenses such as dining out, entertainment, and shopping. Finding affordable alternatives and sticking to your budget can help stretch your funds further.
- Take Advantage of Student Discounts: Many businesses offer discounts to students with a valid student ID. Take advantage of these discounts for purchases such as software, transportation, and dining.
- Work Part-Time: Consider finding a part-time job or work-study position to earn extra income. Working while in school can help cover day-to-day expenses and reduce the amount you need to borrow in student loans.
By following these budgeting strategies, you can effectively manage your college expenses and reduce financial stress, ensuring you can focus on your academic and personal growth.
Early Preparation and Research
- Start researching and visiting colleges early to understand cost differences.
- Apply for financial aid, grants, and scholarships well before deadlines. Don't forget to check out JELF's curated list of financial aid options (not including JELF itself!) here.
Living Arrangements
- Living On-Campus: On-campus housing can often be more convenient and sometimes more cost-effective than off-campus options. It typically includes utilities and other amenities, and you may save on transportation costs by living close to classes and campus facilities.
- Off-Campus Housing Options: Look for less expensive off-campus housing alternatives. Consider sharing an apartment or house with one or more roommates to significantly reduce rent and utility expenses. Additionally, becoming a resident assistant (RA) can offer substantial savings on room and board costs, sometimes even covering them entirely.
- Campus Dining Plans: Take full advantage of campus dining plans to avoid unnecessary food expenses. Use meal swipes and dining dollars wisely, and plan your meals to minimize additional grocery or dining-out costs. Look for discounts or promotions offered by campus dining services, and consider opting for meal plans that best suit your schedule and eating habits to avoid wasting unused swipes or funds.
Textbooks and Supplies
- Buy used or digital textbooks, or utilize library resources when possible.
- Sell textbooks back or participate in book swaps at the end of each semester.
Many retailers and service providers offer discounts for students. Always ask and take advantage of these opportunities. Here is a list of just some of the types of student discounts that often exist.
Technology and Software
- Discounts on laptops, software, and accessories from major tech companies.
- Free or discounted access to popular creative and productivity software.
Streaming Services
- Reduced rates on music, video, and other entertainment streaming services.
Transportation
- Discounts on public transit, train, and bus fares.
- Reduced membership rates for car-sharing services.
Clothing and Retail
- Discounts on fashion, athletic wear, and accessories from various retailers.
Food and Dining
- Discounts available at some fast-food chains and local restaurants near campuses.
Insurance
- Affordable student health insurance plans through colleges.
- Good student discounts on car insurance from major providers.
Entertainment
- Reduced admission prices at movie theaters, museums, and zoos.
- Discounts on tickets for concerts, sports events, and other entertainment.
Travel
- Discounted flights, accommodations, and travel packages for students.
- International student discount cards for various services and experiences.
Books and Supplies
- Discounts on textbooks, school supplies, and rentals from major bookstores and online retailers.
Financial Services
- No monthly fees on student bank accounts.
- Student-focused credit cards with rewards and no annual fees.
Fitness and Wellness
- Reduced rates for gym memberships and fitness classes.
Tips for Maximizing Student Discounts
- Always Ask: Inquire about discounts when shopping or dining.
- Carry Your Student ID: Keep it handy for verification.
- Utilize Student Email: Sign up using your .edu email address.
- Stay Informed: Use websites/apps that list student discounts.
By taking advantage of these general categories of student discounts, students can save money and make their college experience more affordable.
Financial Aid Tools for Today's Students
To better understand all the different types of financial aid available, you can visit the website for the FAFSA. This is the official U.S. government website for federal student aid, and it provides comprehensive information on grants, scholarships, work-study, and federal student loans.
The key is to explore all the different financial aid options, as there are many opportunities for students to get help paying for their education, even if they don't initially qualify for need-based aid. Thoroughly researching the available resources can make a significant difference in a student's ability to afford college.
The FAFSA (Free Application for Federal Student Aid) is a form that must be submitted by current and prospective U.S. college students each year to determine eligibility for student financial aid.
After submission and processing, the applicant can access their FAFSA Submission Summary (FSS).
Note: FAFSA is just the financial aid application. After filling it out, an applicant will learn what aid they may qualify for from their school or university.
Main criteria for FAFSA (for a complete list, visit FAFSA):
- U.S. citizen, U.S. national, or eligible non-citizen
- Valid Social Security number
- Enrolled or accepted as a regular student in an eligible degree or certificate program
- Maintains satisfactory academic standing
- High school diploma or GED
- Signs certification statement stating that:
- They are not in default on a federal student loan and do not owe money on a federal student grant and
- Federal student aid will only be used for educational purposes.
The Student Aid Index (SAI) is calculated using information from your FAFSA, including income, assets, and applicable family circumstances. Colleges use this number to help determine eligibility for need-based financial aid.
Annual federal loan limits vary by year in school, dependency status, and program. Your school’s financial aid office determines your eligible borrowing amount.
An unsubsidized federal student loan is a type of student loan offered by the federal government where interest begins to accrue from the time the loan is disbursed, regardless of whether the student is still in school or during any deferment periods. Unlike subsidized loans, the borrower is responsible for paying all the accrued interest, which can be paid while in school or added to the principal amount of the loan, increasing the total amount to be repaid. These loans are available to both undergraduate and graduate students, and financial need is not a requirement for eligibility, though students can choose to defer the payments until after graduation.
The figures below are annual borrowing limits, not guaranteed awards. Your eligible amount depends on your year in school, dependency status, enrollment, cost of attendance, other aid, and applicable program rules.
Dependent Undergraduate Students:
- Freshman: $5,500
- Sophomores: $6,500
- Juniors / Seniors: $7,500
Most undergraduates receive a subsidized portion of their Federal Direct Loan. However, this depends on demonstrated financial need.
Graduate Students:
For borrowers subject to the rules effective July 1, 2026, annual Direct Unsubsidized Loan limits are $20,500 for graduate students and $50,000 for students in qualifying professional programs. A limited exception applies to some continuing students; ask your school which limits apply.
Federal financial aid includes several types of support, including the programs below.
Federal student loans are loans provided through the U.S. Department of Education to help eligible students and families pay for education. They generally have fixed interest rates and may offer repayment options and borrower protections not available with private loans.
There are many different types of federal loan programs:
- Federal Work-Study Program – Federal Work-Study helps eligible students earn money through part-time jobs on or off campus. Students generally apply for available positions; an award does not guarantee a job.
-
Direct PLUS Loans – These are federal loans that graduate or professional students and parents of dependent undergraduate students can use to help pay for college or career school.
- Graduate PLUS Loan - Beginning July 1, 2026, Grad PLUS loans are unavailable to new borrowers. A temporary exception may apply to students who were enrolled in their graduate or professional program by June 30, 2026, received a federal Direct Loan for that program before July 1, 2026, and continue in the same program at the same school. The exception generally lasts for the shorter of three academic years or the program’s remaining expected duration. Students should contact their school’s financial aid office to confirm eligibility and how long the exception applies.
-
- Parent PLUS Loan – This is a federal loan offered to parents of dependent, undergraduate students who are enrolled at least half time at participating and eligible post-secondary institutions. Good credit, not financial need, is required.
- To receive a Parent PLUS Loan, the parent(s) must not have an adverse credit history. Parent PLUS borrowing is generally limited to $20,000 per academic year and $65,000 total per student, combined across parents.
- A limited exception allows qualifying families to continue borrowing up to the cost of attendance minus other financial aid. Contact the school’s financial aid office to confirm which limits apply.
- Repayment begins 60 days after funds are disbursed but may be deferred for a 6-month period after the student graduates. If a parent borrower is unable to obtain a PLUS loan, the undergraduate dependent student may be eligible for additional unsubsidized loans.
- To receive a Parent PLUS Loan, the parent(s) must not have an adverse credit history. Parent PLUS borrowing is generally limited to $20,000 per academic year and $65,000 total per student, combined across parents.
- Parent PLUS Loan – This is a federal loan offered to parents of dependent, undergraduate students who are enrolled at least half time at participating and eligible post-secondary institutions. Good credit, not financial need, is required.
-
Pell Grant – This is a need-based grant which is awarded to students with the highest calculated financial need and does not have to be repaid. The maximum Pell Grant is currently $7,395 per year. Eligibility is based on a financial formula. These grants are limited to students with financial need who have not earned their first bachelor’s degree.
-
SEOG (Supplemental Educational Opportunity Grant) – Federal grant awarded to Pell Grant recipients who have the highest need. Schools receive a limited amount of SEOG from the federal government, so not all Pell recipients will receive it. Amounts range from $100 to $4,000. The SEOG does not have to be repaid.
| Loan Type | Description |
|---|---|
| Subsidized Federal Direct Loans | A subsidized Federal Direct Loan means that the government will subsidize the interest while the student is enrolled or in deferment. This loan is awarded on the basis of financial need. Approximately 2/3 of subsidized Federal Direct loans are awarded to students with family gross incomes under $50,000. |
| Unsubsidized Federal Direct Loans | An unsubsidized loan means that the student is responsible for paying the interest on the loan from the minute the loan is granted. Students may, however, have payments deferred until after graduation, at which point they may take 10-25 years to repay. Eligible students may qualify regardless of financial need. The interest that accrues is capitalized and added to the principal. |
2026–27 Federal Student Loan Interest Rates:
| Loan Type | Interest Rate |
|---|---|
| Direct Subsidized and Direct Unsubsidized Loans -undergraduate only | 6.52% |
| Direct Unsubsidized Loan - graduate and professional students | 8.07% |
| Direct PLUS Loan - parents and eligible graduate or vocational school borrowers | 9.07% |
Graduate students are automatically considered “independent” of their parents for purposes of obtaining federal loans and completing the FAFSA, regardless of their age. This means that their eligibility for federal aid is determined based on their own financial situation, not their parents'. Medical students are independent for federal student aid purposes and do not provide parental financial information on the FAFSA. However, some health-professions programs may request parental information when evaluating certain institutional or federal health-professions aid. Check each school’s requirements to be certain.
Essential Documents for Your Financial Aid Application
Applying for financial aid can feel overwhelming, but having the right documents ready will streamline the application process and increase your chances of receiving the maximum amount of aid possible. To ensure you submit a complete financial aid application, use these tools below to learn about the essential forms and records you may need to provide.
Remember, the specific documents required may vary depending on your personal circumstances and the type of aid you are seeking, so be sure to check with your school's financial aid office for any additional guidance.
These documents encompass the most common items required for federal, state, and institutional financial aid applications. Depending on your unique situation, you may need to provide some or all of these materials. Take the time to carefully review each item and have them readily available when you begin filling out your financial aid forms.
If you have any questions or need assistance gathering these materials, be sure to reach out to your college's financial aid department for support.
If a student is starting a new school or program, they must typically have available the email or letter from their school, received upon acceptance.
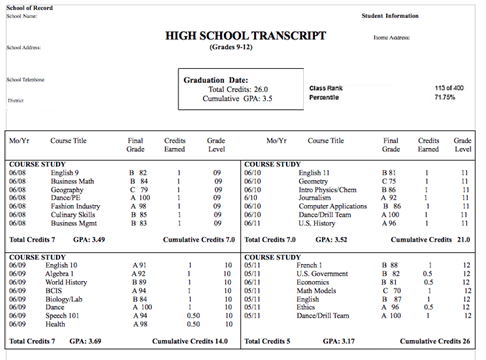
Financial aid applications often require a student's unofficial transcript (i.e. grades) through their most recently completed semester of school. This must include the student's cumulative GPA. Students typically do not need to pay for an 'official' transcript; a screenshot is fine (see below).
Students will find their Financial Aid Award in their school's student portal. It is important to ensure that this is the award for the academic year in which they are applying for a loan, not a previous year's award. While each school’s award summary will look different, students will typically need the financial aid award that has been ACCEPTED, not just the award letter showing what the student has been offered. These are the total federal loan amounts that students are offered for each academic year:
| Level | Annual Borrowing Limits |
|---|---|
| Freshman | $5,500 |
| Sophomore | $6,500 |
| Junior | $7,500 |
| Senior | $7,500 |
| Second Bachelor’s Degree | Varies by dependency status and federal eligibility rules |
| Graduate Student | Up to $20,500 annually for graduate students; eligible professional programs may have higher limits |
Each school’s award summary looks a little bit different. Here is a sample: 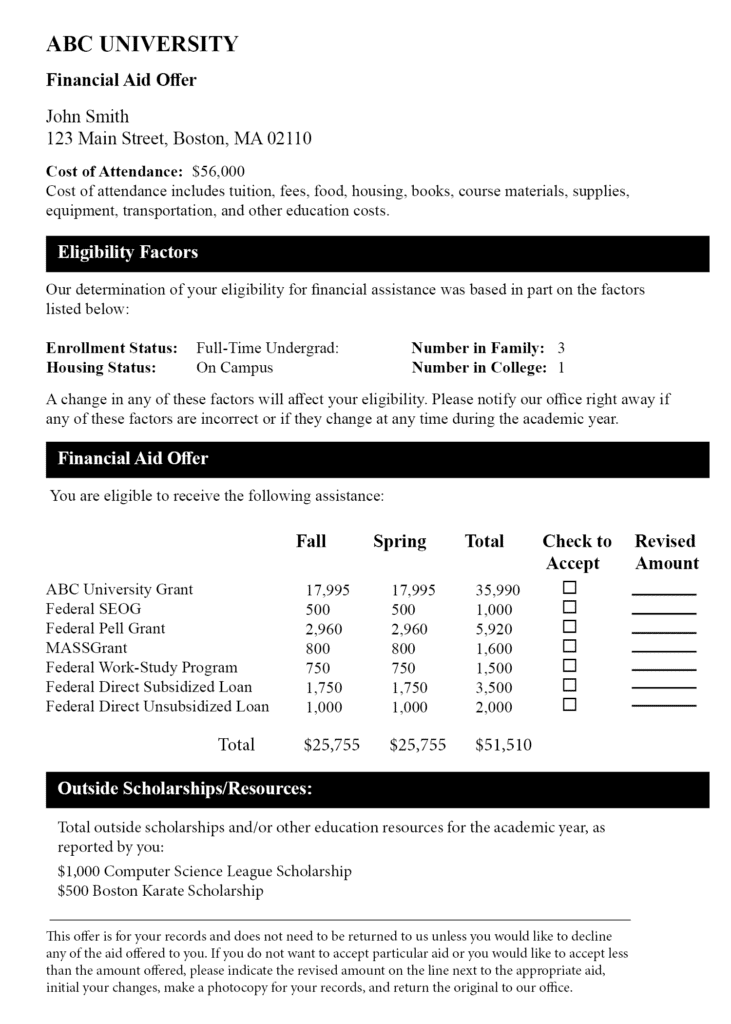
A school's cost of attendance can be found in a student account, the school’s website or within the student's financial aid letter. This document should show the expected breakdown of costs such as tuition, housing, meals, fees, and other educational expenses. If there are additional costs related to a student's program, students should explain this, including the amount and what the amount covers, wherever possible. Sample Cost of Attendance 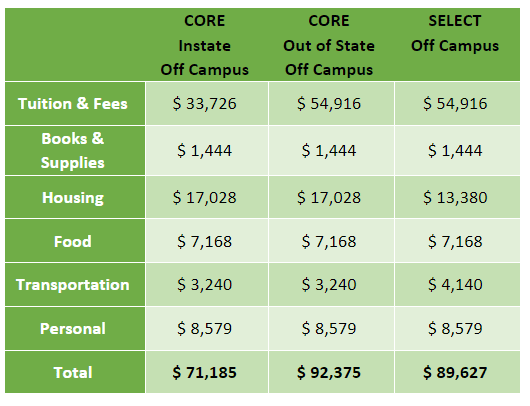
The FAFSA Submission Summary (previously known as the Student Aid Report or SAR) summarizes the information a student submitted on their FAFSA and provides information about financial aid eligibility based on that information. After a student's FAFSA form is submitted and processed, they will receive an email from FAFSA with instructions on how to access an online copy of their FAFSA Submission Summary. This will include the estimated eligibility for federal student loans, a Federal Pell Grant (if student qualifies for one), the Student Aid Index (SAI) and whether the student has been selected for verification. Some students are selected for FAFSA verification, a routine process in which a school confirms information provided on the FAFSA. Selection does not mean the student has done anything wrong. Students should submit any requested documentation by their school's deadline to avoid delays in receiving financial aid.
Once your FAFSA has been processed, log in to your account at StudentAid.gov. From your dashboard, select your processed FAFSA submission and choose “View FAFSA Submission Summary” to access or download your summary.
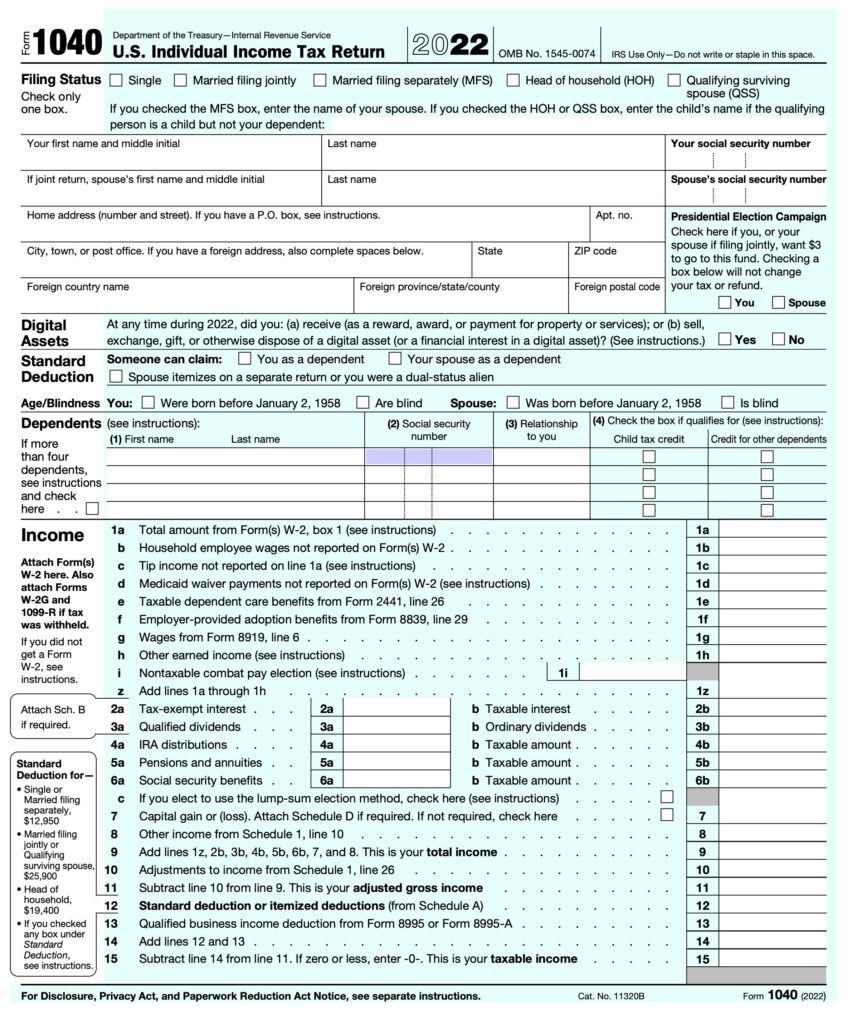
If a student has been employed and filed taxes, they may need to submit their most recent tax return.
Sample Tax Document:
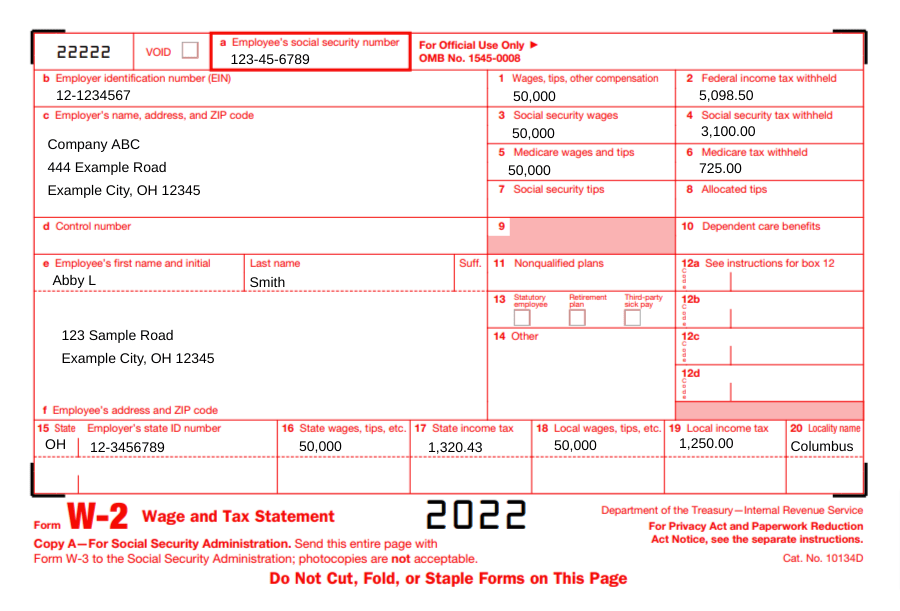
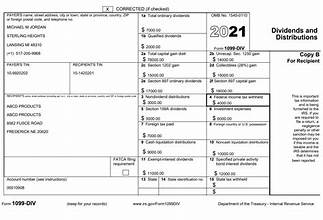
If a student worked during the school year, they may need to send in either the W-2 or 1099 Form to verify employment.
SAMPLE FORM W-2:
SAMPLE FORM 1099:
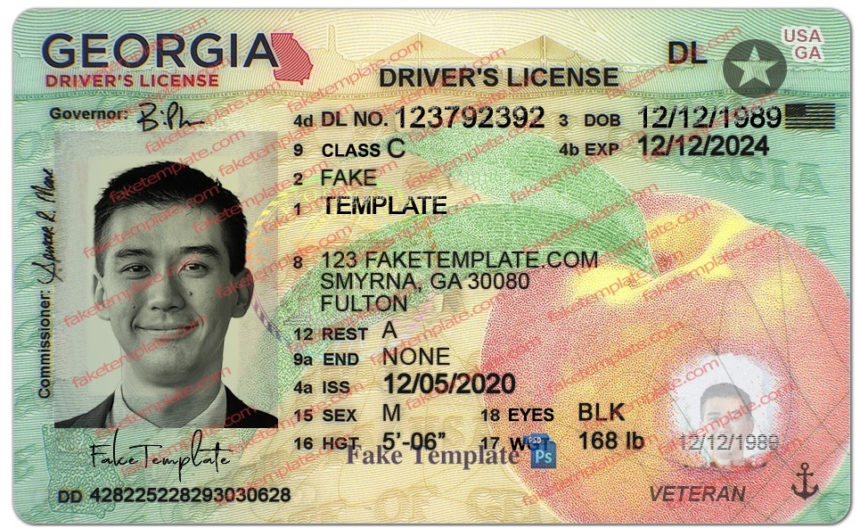
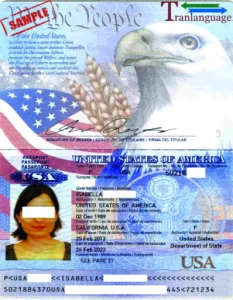
Students will need to upload an image of their driver's license, state ID or passport. The image uploaded must include a photo of the student.
Examples:
Scholarships and More
In addition to our student loan offerings for Jewish students, JELF also provides a list of scholarships and other financial aid options that all students can access. This comprehensive resource can help you identify and apply for additional funding opportunities to support your educational goals.
JELF's College Readiness Test
Whether you are in a preschool stage -- or already in high school -- JELF's roadmap will help you navigate the financial aspects of college planning with confidence and ease.
JELF Application FAQ
JELF (Jewish Educational Loan Fund) is a non-profit organization that provides interest-free loans to Jewish students in need. JELF's mission is to enable Jewish students to access educational opportunities that may otherwise be out of reach due to financial constraints. JELF loans can be used for a variety of educational expenses, including tuition, room and board, textbooks, and other approved costs. Students can begin a JELF application anytime. Apply by April 30 for the next full academic year or September 30 for spring and/or summer assistance.
To be eligible for a JELF interest-free loan, a student must:
- Identify as Jewish (must be Jewish by lineage or conversion; Messianic Jews are not eligible.)
- Be a U.S. citizen or have lawful immigration status. Student visas do not qualify.
- Be a permanent resident of JELF’s five-state region: Florida, Georgia, North Carolina, South Carolina, or Virginia (excluding metro DC).
- Be enrolled full-time in a degree- or certificate-granting program at a U.S.-accredited institution.
- Demonstrate financial need.
- Maintain a GPA that aligns with their school’s academic progress standards.
JELF serves students who have permanent residence in the following states:
- Florida
- Georgia
- North Carolina
- South Carolina
- Virginia (excluding metro DC)
Why? This region was established when JELF was founded as the Hebrew Orphans’ Home (HOH) in 1889, serving B’nai B’rith District #5, which continues to be JELF’s service area.
Residency Requirement:
- Students must have lived in the five-state region for at least one year before the application deadline.
- Proof of residency can include legal documents such as a driver’s license or tax return.
- Students can attend any U.S.-accredited school, regardless of location.
For Hebrew or Jewish Free Loan agencies outside JELF’s five-state region, you can find a list through the International Association of Jewish Free Loans.
JELF provides funding for students to attend any U.S.-accredited college, university, or vocational school of their choice.
JELF takes both the total cost of the student’s education as well as the family’s total resources into account. Defining need is personal and varies among families. Need is based not only on household income but also the number of individuals in a household, as well as a medley of other factors related to health or employment that may directly alter what funds exist for a student’s higher education.
Learn more here about JELF’s process for determining each applicant’s loan amount.
JELF loans are based on financial need, not a student’s GPA. In order to be eligible (or stay eligible) for funding, all loan recipients must prove to be in good academic standing each semester.
JELF loans are available for students attending U.S.-accredited universities, vocational, or CTE (Career & Technical Education) programs. If a school is eligible for FAFSA, it meets JELF’s criteria.
Although most international universities are not FAFSA-eligible, JELF has funded programs outside the U.S., such as the American Medical Program at Tel Aviv University in Israel, which is accredited through NYU.
To determine if an international school qualifies for FAFSA, please contact the university or program directly.
JELF provides “last dollar” funding – filling in the final gap after all other financial aid has been applied.
This means that students are required to accept all federal Direct Subsidized and Unsubsidized Loans offered. These loans typically carry the lowest interest rates and most flexible repayment terms, and accepting them is a requirement before JELF can step in to help. However, JELF does not require families to take out Parent PLUS or any other high-interest private loans.
Yes! Thanks to the Judith and Aaron Alembik Endowment, JELF has established a dedicated fund specifically to support the children of Jewish clergy. This endowment ensures that eligible clergy children have access to JELF’s interest-free loans as part of the regular application process, helping them pursue higher education without the burden of high-interest debt.
This fund is not intended for students who are studying to become rabbis, cantors, or other Jewish clergy themselves. Rather, it is intended to assist the children of clergy in financing their undergraduate or graduate education. To learn more about this unique opportunity and eligibility requirements, visit jelf.org/clergy.
Not necessarily. JELF evaluates each application based on eligibility, demonstrated financial need, and available funding. Loan awards and amounts are determined through JELF’s review process. Students who are not approved for assistance may apply again in a future application cycle.